Friday, April 29, 2022

Atalaya Copper

Atalaya is a small, copper miner, producing from a single mature mine in Spain.  Its listed on AIM/TSE.  Mkt cap is around 700m Euros.  I was attracted by the dividends.

Operations

They have been producing from their Cerro Colorado pit in the RioTinto mine near Seville (south Spain) since 2016.  From their 2022 production guidance (15.5Mt/year) and Proven Reserves on their website (128Mt @ 0.41% cutoff), the mine has 8 years life remaining.  Their June 2021 reserve estimate gives proven reserves of 139Mt @ 0.38% Cu, estimating a 12 year lifespan (ie: 11 years from now).  So this mine's lifespan is somewhere between 8 and 11 years.

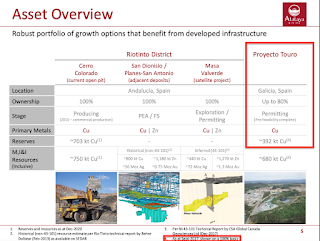
They have new mine (Touro) in the north of Spain undergoing permitting. This has half the reserves and roughly half the potential production of Cerro Colorado:

And like any mining company, they have a number exploration projects ongoing.  Most are surrounding RioTinto:

Finances

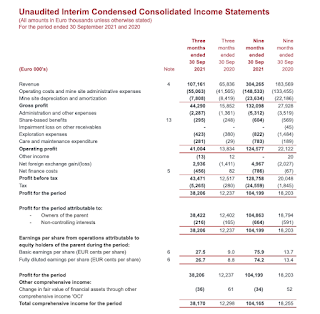
The finances look simple and clean.  Normal looking income statement: 


They were profitable in 2020.

Low debt, net cash position.

They declared their first dividend late last year, and plan to payout 30-50% of free cashflows this year onwards.  The (annualised) yield based on that is 8.6% (at a share price of 4.50 GBP).  And that was 45% of earnings.  Can't extrapolate that into the future since it all depends on the copper price.

Risks

They are producing from a single mine.  Anything that goes wrong there affects their entire production.

Cerro Colorado only has an 8-11 year lifespan.  Production should start soon at Touro, but this is only half the size.  They need more projects to work out, just to replace Cerro Colorado.

Not much Geopolitical risk.  I like to own copper production away from Chile and Argentina, who are raising resource taxes.

I think Spain's gonna have a currency crisis and leave the EU, but that doesn't affect mining.  And I think Spain is not as safe a jurisdiction as Canada or Australia, but its better than Latin America or Indonesia.  With mining you can't be choosy.

Misc

Spain has a 19% withholding tax.  Should be 5% for Singapore residents (p7), but I'll need to see what Interactive Brokers charges.

I got this idea from an 2021 interview (paid link) on CruxInvestor.  He starts talking about Atalaya's projects at 22:00.  Dividends and acquisitions/mergers at 27:00.  Expansion at 39:40.

Conclusion

Production is from a single mature, low grade mine.  Sustainable for 8-11 years.  They are profitable by running it efficiently.

Their long term future depends on bringing on production from the areas surrounding Cerro Colorado.  This ends up being a binary event - either one of them works or it doesn't.  There is a lot of luck in mining.  The most likely place to find new reserves is next to an existing mine.

Saturday, April 23, 2022

Quick notes on Woodside Energy (ASX:WPL)

Largest Australian LNG producer, with long-life conventional projects.

Its a well-covered blue chip, so no point over analysing it.  I just want to get a feel for their risks and numbers.

GeoPolitical Risk

Very low.  All 2021 production and 94% of their 2P reserves were from offshore Australia.  So its is safe from any wars/revolutions in Russia, Asia or the Middle East.  About half their 2C gas reserves are in Canada, and they have some development in Senegal.

Some China risk.  30-40% of Australia's LNG exports go to China.  Probably the same proportion for Woodside's.  If China attacked Taiwan, these would need to find a new market.  That event would probably tank the LNG market.

Some ESG risk: In 2021 19% of Woodside shareholders vote to "manage down" oil and gas production.  Australia is pretty woke.

Reserves

After dropping for the past 7 years, 1P and 2P reserves doubled in 2021, the increase being transferred from their 2C reserves (p56), almost all of it to due to first time reserves classification of the Scarborough development (West Australia) (p145) (p26).

Taken at face value, they have 12 years of 1P gas reserves remaining.

Balance Sheet

Net debt is low at 3.7bn.  Less than 1X 2021 EBIDTA (a good year).  Or 2X 2020 EBIDTA (a bad year).

Historical Cashflows

They paid high dividends, even in 2020's downturn.  I'm a bit uncomfortable with this.  I did the numbers below to get a feel for their last past 10 years' cashflow generation, capex and dividends.

CashFlows from Ops are usually greater than Cash(out)flows For Investment.  The yellow line is usually positive:

Dividends are high, based on 50-80% of NPAT.  No relationship between cashflows generated and dividends paid out:

Over the period, the average annual cashflow generated (CFO-CFI) was 1.2bn  The average dividend paid out was 1.1bn.  So they paid almost all cash generated as dividends!

These dividends are a little high and could be better used for growth.  But they are probably sustainable - its not a ponzi.  I just dislike cyclical companies that pretend to be something they aren't.

The latest 2021 dividend of USD 1.35 is 80% of NPAT.

BHP Merger

The proposed merger with BHP Petroleum, if done in Dec 2021 (pro forma), would have:
  • Almost doubled the number of issued shares (up 95%)
  • Not increased debt, but added a 4.1 billion provisions (restoration, I think)
  • Increase 1P reserves by 62% (in MMboe - however BHP's reserves are 'oiler', at around 30% oil) (p235)
  • Changed production profile to be 'oilier': up to 30% oil.  Also change production profile from 100% Australian to 15% GOM and 5% Trinidad and Tobago (near Venezuela) (p238)
  • Increased CFO from 3792m to 6314m (up 86%).
  • Increased CFI from 2941 to 4042 (up 37%)
2/3rds of BHP's assets are in GOM.  These have a 20-30 year expected life.  Their Australian assets have a 10 year lifespan (p151):


They expect 400m pre-tax savings annually (p226) in 'synergies' which are not part of the pro-forma numbers above.

From the numbers, I'm guessing the merger maaaaayyy be OK for Woodside shareholders.  If they get their 'synergies'.  They are both Australian companies, so no culture shock.  BHP is a motivated (maybe irrational) seller.

Capex and Production Growth

For Woodside, the term capex means "Cashflow from Investment".

I couldn't find much.  Best I found was 2019 (pre-covid) slides expecting a 2021 peak in capex of 4-5bn (slide 39):

With ramp ups in production volume till 2024-2026 (slide 9):

Actual 2021 CFI was 2.9bn.  Looks like a lot of investment has been pushed back and is still to come.

Presentations and transcripts in 2020 and 2021 don't give long term capex targets, they only give them for the following year.  2022's capex is expected to balloon to 4bn (excluding BHP's assets) (p24).

Conclusion

Blue chip company paying almost all its cashflows as dividends.  I think it will diversify my energy stocks, adding production from a low risk part of the world.

I'll add this to my watchlist.  Not buying it now cause I think the market's going off a cliff in the next 3 months.  And there's a chance that woke BHP shareholders dump their unholy fossil fuel shares once the merger goes through on June 1st.

Misc

Australian WHT on dividends to Singapore residents is 15%.

The main business problem the company has is a rising AUD and costs, if the commodities boom continues.
Tuesday, March 22, 2022

Quick Notes on LendLease Global REIT

I like their current malls, and they have a high yield.  Lets look further.

All numbers are from their unaudited pro-forma 2021 results (for the JEM acquisition - starts p235).

This idea was from Dividend Titan.

Properties

Three properties.  By AUM:
  • 47%: JEM Retail: Heartland mall in Jurong, it shares Jurong east MRT with 1 or 2 other malls.  Leasehold: expiring 2109.
  • 29%: 313@Sommerset: Mall above Sommerset MRT in the city.  Leasehold: expiring 2105.
  • 13%: JEM Office: 12 levels of Grade-A office space.  Leased to Singapore Ministry of National Development until 2045, with a rent review every 5 years.
  • 12%: Sky Complex: Three A-grade office buildings in Italy, leased to Sky Italia (Italian broadcast & pay TV) until 2032 (option to break in 2026), and indexed (three-quarters) to Italian inflation.  Freehold.
I think their malls are quite good.  JEM is at the bustling Jurong East MRT and is usually busy.  Compared to its the neighbouring malls: Westgate is slightly more upmarket, and JCube is too small and far away to have critical mass.  I also like 313@Sommerset: its usually quite busy on weekends, due to MRT traffic, even when neighbouring malls a few blocks away were empty (pre-covid).  Both malls have a good vibe.

I don't like offices, but am comfortable with JEM Office's long lease with 23 years remaining.  Don't know if its indexed to inflation.

I don't like Italy.  Or offices in Italy.  Need to see if Sky Italia takes the option to break the lease in 2026. TV is a dying industry, and Sky Italia should finish its downsizing plan in 2025, meaning less office space.  OTOH, upside in this property may be limited: Under Italian law, upon lease expiry, the landlord must re-offer the lease to the same tenant (under existing terms?), before they offer it to other parties who may be willing to pay more (p143).

Debt

Gearing is 41%.  MAS limit is 50%.

They have 200m of perpetual securities (paying 4.2% pa).  Adding this to debt brings up the gearing to 44 or 45%.  I don't like companies that issue perps, but like bonds, they benefit the issuer in times of high inflation.

A quarter of their debt is denominated in Euros, whereas only 12% of their assets are in Europe.  Thats a bit of a currency risk. The Euro denominated debt is until 2024.

Overall: their debt is pretty high.  I think the next acquisition must be funded entirely by equity.

Incentives

Base management fees are a flat 0.3% of the asset's value.  Incentive fee is 5% of NPI (p326).  Pretty standard for Singapore REITS, though I prefer to see incentives based on a per-unit measurement.  Incentives based on NPI can make them grow for the sake of growth.

Lendlease, the sponsor, holds 26% of the REIT, reducing the chances of them dumping bad properties into it.  I also think that, because they have soooo many properties to dispose of, they would be better off building up this REIT as a reputable longterm investment, rather than just dumping some lousy properties into it in the first few years.

They've only done one acquisition since they listed - the big JEM one.  It should be ~10% DPU accretive, increasing DPU to 5c.  Lets see how that goes.

Future Growth

If they want to grow in Singapore, the sponsor has 2 properties:
  • Parkway Parade: a mixed office/retail mall.  A very old mall from the 80's.  Not near an MRT, though its in a place where residents have cars.
  • Paya Lebar Quarter.  Large mixed use development, directly accessible from Paya Lebar MRT.  I haven't seen it.  Sounds busy, but there are competing malls next door.
Lendlease also has a lot of mixed use properties the world.  I'm sure they will be passed down to the REIT.  Ten years from now, the REIT will look very different...which is why they have the word 'Global' in their name.  I'm cautious on that, as I have no way to know the prospects of these overseas properties, and I don't like offices in general.  We have to trust REIT management to take care of shareholders, and their track record is not long enough now.  I probably would limit myself to  5% position.


Conclusion

I bought a 5% position at 76.5c this morning, as their share price dropped due to news of the preferential offering.  

Just realised that the Preferential Offering takes place 30th March, if I subscribe to it (@ 72c per share), I'll have a 6.5% position.  We'll see....


Update 10th April 2020: They issued less shares than expected, and issued 200m perps.  I calculate their new pro-forma DPU would be 4.8c.

Thursday, March 10, 2022

Bought Oil again

Bought a 5% position in oil producers again with the correction in WTI over the past 2 days: 2% CNQ, 2% Equinor, and 1% Pretobras.

Will write more here on the weekend.

Update: Friday 11th March.

Why I bought oil stocks:

  • They are still not expensive.  CNQ for example is trading at 12X TTM earnings, when WTI averaged $68.
  • They are going up.  Technical Analysis 101: buy stuff thats going up.
  • There may still be a shortage of oil, same inflation story as before the war.  The war has removed Russia's exports of 5m bpd (~ 5%) from the market.  Russia's production will drop without Western technical assistance.
  • Peter Zeihan raised a point: If Russian crude can't be exported through their eastern ports, and the backlog is too big, they need to stop production, which can take years, or even decades, to recover from.
The risks:
  • Biggest risk is a peace deal between Russia and Ukraine.  Israel is trying to broker peace, and while both Putin and Zelensky have gained popularity in the war, they both stand to lose if it drags on.  Zelensky will lose his country, and Putin should be remembering Afghanistan.  I give peace a 1/3rd chance.  If it happens, I'll be happy for the Ukrainians, but would wish I had bought my oil stocks cheaper.
  • Avoid companies operating in the potential warzones of the Persian Gulf, Eastern Europe and Russia (doh!), and the South China Sea.  And Africa may not be that stable if food prices soar,
  • The US president has the power to stop crude exports, which would make WTI trade at a discount to Brent.  This is a risk for US and Canadian producers, and is the reason I'm not buying XLE (to hold together with CNQ).
  • Petrobras is risky and may go to zero if nationalised (or if asked to subsidise the country).  Brazil has a bad track record on this.
  • I am uncomfortable buying when everyone else is.  Energy might be the new FAANG.  Could be, but I'm still uncomfortable.  Need to remind myself that the crowd is correct in the middle of a trend.  And thinking that your'e smarter that everyone else does not make you money.
You pays your money and you takes your chances.

Thursday, March 3, 2022

Sold Kazatomprom & bought Sput

Sold Kazatomprom, at USD 25.25.  Loss of ~ USD 4.7K, or 21%.

Its no longer a dividend play who can benefit from rising Uranium prices.  Most of their Uranium is shipped through Russia.  Once that is cut off, they can only sell to China.  Add to this the risk of holding shares in a Soviet satellite state.

Counting my gold as cash, I'm 6 or 7% in cash.  And I'd probably be comfortable adding another 10 or 15% in margin.  When the time comes....

Update: 7th Mar: Replaced it with Sprott Physical Uranium Trust (U.UN), 1140 shares @ CAD 16.54.  Hard to find Uranium companies worth buying, easier just to bet on Uranium itself directly.  Looks like it tried to correct yesterday but failed.  I'm expecting the stock market correction to continue for a few months, but this may not affect Uranium.

Tuesday, March 1, 2022

Lost in Russia

MOEX has been closed for the past 2 days.  They are considering to not allow foreigners to sell, and not paying dividends to residents of countries that places sanctions on Russia

Nothing I can do about it, so best to just write off my Russian shares.  Its a 6% loss for my portfolio.

I knew the risks when I bought them.

I'm still looking at:

  • Dividend stocks/REITs to replace Netlink Trust in my portfolio
  • Stuff to buy in the correction I expect between now and June.  Copper.  Oil if it corrects.  Maybe some crypto.
For now, I still think we're in a correction.

Friday, February 25, 2022

Sold Gazprom

In 2020, Gazprom sold 78% of its gas to Western Europe.  The story was that it would keep growing through Nordstream 2 and increasing exports to China.

Now Nordstream 2 is finished.  And Europe is likely to wean itself off Russian gas in the next few years.  Its a matter of survival.  So Gazprom is no longer a long term dividend story.  

Would I buy at at its current price?  No.  Too unpredictable.  So out it goes.  Sold on the bounce tonight.  Loss of USD 2K, or around 14% (includes dividends received).

I need to think about my other Russian stocks.  Oil, fertiliser and metals are harder than piped gas to place sanctions on. But oil production probably falls long term as the Russians need western technical expertise to keep their equipment running and drill new wells.


Bought back 1% more gold after it corrected yesterday.  Now back at a 6% position, and want to buy more.  With 6 rate hikes priced in (after the start of the war), thats still 5 too many.