I've been caught wrong-footed by Russia's Ukraine invasion:
I had an 11% position in Russian (and Soviet block) commodity companies. Now down by about 1/3rd. Hard to tell whats priced in. I do not know if the US will really place sanctions on Russian commodities (except for piped gas). Overall, I feel OK about it: when you roll the dice, sometimes you lose.
Worse, I had sold my oil, looking to buy back in June. Its since gone parabolic.
I've been selling my gold position as it moves up. Now its 5%. Short term, I don't think it goes up much more, the uncertainty over Ukraine has been resolved. In a few months, it may still rise as market expectations of interest rate rises drop.
I still think we get a market correction in June. Hopefully I get a chance to buy oil/commodity producers then.
Everyone has a plan till they get punched in the mouth.
Bought a 2% position in Nornickel (MOEX:GMKN). Taking advantage of the low prices from the Ukraine situation. Safer to buy on MOEX directly, than to buy the US-listed ADRs.
Nornickel is a low cost producer of:
Palladium. Used as a catalytic converter for petrol engines. Its used in greater amounts for hybrids, so may have rising demand from this. Not used in EVs.
Nickel. Used to strengthen steel for construction. May have increasing demand for lithium-ion batteries.
Copper. Used to transmit electricity. May have increasing demand if China doesn't slow its copper usage.
Its got a trailing 9-month yield of 10%, but it all depends on metal prices.
I now have 11% exposure to Russia (includes Kazakstan), thats enough.
Ukraine
Now I join all the instant experts on Ukraine.
The facts:
Russia can easily take Ukraine.
But it may be too costly for them to hold it. Ukraine has 45m people.
Any invasion must start by March. Before Spring turns the ice to mud. Then the invasion has to wait til Summer.
Sanctions don't bother Russia, they have high reserves.
I'd put the odds at:
70% chance that Putin gets some meaningful concessions and pulls back.
30% chance of war. The Russians need to take Ukraine for defensive purposes (from their point-of-view), and this is the last chance they get.
The repercussions of a war:
Gazprom goes to zero. Germany looks elsewhere for energy.
Apart from (piped) natural gas, I believe sanctions won't work against a commodities exporter. Commodities are fungible, and in short supply at the moment. This is like China trying to stop buying Australian coal.
The only way I can see sanctions working is if the US plays hardball and stops trade with any country that trades with Russia. Thats is: an excuse to them to de-globalise.
Interactive brokers is a US company and may stop access to MOEX.
Taiwan invasion becomes more likely?
Some of the better commentary on the Ukraine situation:
I think we get a market correction this year followed by a wild boom into 2023/24. Beyond my boring dividend stocks, I'm looking for speculative risk-on assets to hold in the coming melt-up. Stuff that can make me rich.
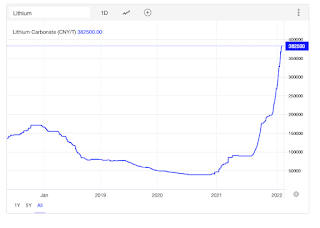
Lithium might be one.
Its a way of playing the EV boom without having to pick winners among car or battery manufacturers. For a commodity, a rising tide lifts all boats.
Lithium Demand and Supply
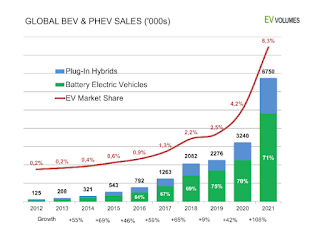
The textbook way to estimate a commodity's price is to model future demand against supply and see how they balance out. With lithium its pointless. Typical estimates have EV sales and lithium supply doubling from 2022 to 2025, then doubling again by 2030. Both the supply and demand charts look exponential. With such high growth rates, small change makes a big difference. Any numbers you toss around are a wild guess.
On the demand side: I think electric vehicles are becoming mainstream in developed countries. Ford's F150 lightning selling out, for example. I think they become something that normal people want to drive. EV's had an 8.3% market share in 2021, they have plenty of way to go:
For supply: while you can find lithium compounds anywhere in the world, there may be a shortage of mines and processing facilities. Modelling this more than a three years out is impossible as we don't know which mines will come online and which will be cancelled. One model both indicates a slight surplus in 2022, with deficits in 2023 and 2024 (Matt Bohlsen's Jan 2022 Model - paid link).
The Lithium Industry
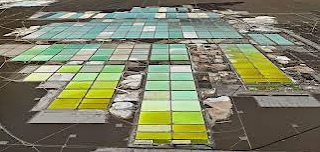
The traditional method of extracting lithium carbonate is from brine. Lithium rich waters are pumped into evaporation ponds in the desert, and left to evaporate for 2-3 years. The time taken depends on rainfall. During that time production cannot respond to changes in demand. This method is the lowest cost, accounts for around 35% of lithium production, and is used in South America.
The remainder is produced from hard rock. Ore is crushed, then undergoes several separation processes to produce a concentrate. This uses more energy and is more expensive, but takes less time. Its used in Australia, which acts as the swing producer.
It usually takes 5-7 years to start up a lithium mine. Sometimes up to ten years.
Future potential supply sources are:
New extraction techniques being researched. Clay mining is being trialled.
The second largest producer, SQM, has too much exposure to Chile/Argentina with their new mining tax hikes. I already have exposure to these through Lundin Mining and SCCO, don't want more.
GanFeng Lithium (HK:1772):
3rd Largest Lithium producer, with an estimated 17% market share.
75% of their 2020 gross profit and 86% of 1H21 gross profits were from lithium, the remainder from batteries.
Also profitable in 2020, excluding fair-value gains.
Debt is around 5-6X 2020 CFO. A bit high, but not in any danger of going under.
Aggressive expansion plans to increase their capacity to 200,000 tonnes LCE per year by 2025. Thats 4 times their 2019 production.
They regularly issue convertible bonds or new shares.
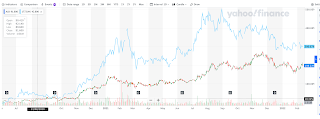
Both these companies are correlated enough to be pretty much the same trade. With GanFeng being higher risk.reward:
Conclusion
When your'e buying into a growth industry, you can't value it. I think the best you can do is:
Wait for the right time: when its plausible that demand could outweigh supply, and when risk-on assets are going up.
Buy something that won't go to zero. Or if it can, position size appropriately.
Ride the trend. Number go up.
Just to be clear, I'm not buying now. Maybe in a few months.
This bear market will give me a chance to buy BTC.
What is Bitcoin?
Bitcoin is a trustless and distributed database/network running a shared ledger. If that means nothing to you, the best explanation is:
If you buy bitcoin you need to watch the 30 minute video to understand it is. Even if your'e just trading, you have to know what it is so you can risk manage and position size it (can it go to zero?). Its also the foundation for understanding other cryptocurrencies. Chapter One of Crypto for Dummies.
Key points derived from the above:
Bitcoins are just the unit of currency on a shared ledger. There's a maximum of 21 million of them.
No one controls the bitcoin network. All miners together agree on changes to the ledger by following the protocol. This is the mind blowing thing about it - its a ledger/currency with no centralised exchange or backing. The closest thing in the real world is gold.
The only way to control is to gain control over more than 50% of the mining power. Then the next valid block is whatever you say it is.
No one can just change the ledger (or the code implementing it). If you did this, you are creating a new, separate network. You could call it "Bitcoin2" but its not worth anything, unless the rest of the world agrees with you and joins your network (starts mining on it).
Bitcoin transactions are slow by design. By itself, bitcoin is not suitable to use as everyday money.
Holding a bitcoin just means it is assigned to an address (public key - just a long string of digits) to which you - and only you - have the private key (another string of digits, specific to that public key). If someone else gets the private key, they can transfer the bitcoin. If you lose the private key, you lose (access to) the bitcoin forever.
All bitcoin transactions are stored on the blockchain forever. Someone with enough resources and motivation (like the FBI or IRS) could trace the trail of addresses back to the money initially used to buy it. I wouldn't use bitcoin at a strip club, for example.
Bitcoin Trends
Increasing Adoption
As bitcoin is more widely adopted as a store of wealth, it becomes more valuable, so more likely to be adopted. A bit like gold, which is valuable because its rare, fungible, (a bit) divisible, and because everyone else values it. As bitcoin was the first electronic and trustless store of value, it has a first mover advantage and a network effect.
If the lightning network gains enough users, bitcoin may end up being used as everyday money.
Cyclical Trends
Bitcoin is 'digital gold' but it doesn't trade like it. It trades as a risk on commodity.
Before 2020, it was uncorrelated with the S&P 500, after that it correlated weakly:
I'm waiting for the end of this correction to buy it.
Threats
Regulatory Threats
Bitcoin is not under threat from the SEC, it is not a security. It never underwent an ICO. The anonymous founder of bitcoin, Satoshi Nakamoto, mined his coins it along with everyone else after introducing it in 2009. He never issued bitcoins to "investors".
The IRS is asking about cryptocurrencies 2021's tax return. While this makes it harder to use bitcoin as money (having to calculate capital gains tax every time you 'sell' to BTC to buy something), it means the government is unlikely to ban it.
Decentralisation
The bitcoin network is highly decentralised. No one controls it, and even the US government could not shut it down if they wanted to. The best they could do is to limit people from buying it on (most) exchanges.
China used to have a 75% share of (power used in) bitcoin mining, potentially giving the CCP control of the network. After their crackdown on bitcoin mining last year, they now have less than half. This was the biggest threat to the bitcoin network.
Technical Issues
The protocol is simple and has been tested for years, with no bugs or exploits.
Quantum computing will be a threat later, allowing a private key to be derived from its public key. I think there are quantum resistant algorithms that the bitcoin network can fork to. But I'm not sure (quantum-proof, or quantum resistant?).
ESG
This is the biggest long term threat. Bitcoin scores poorly on ESG criteria, because of its power usage. Other cryptocurrencies that don't use Proof-of-work may be more widely accepted.
USDT and Leverage
This is the biggest short term risk.
Tether (USDT) is a stablecoin commonly used to buy bitcoin. Its issued by a Hong Kong company, who says the USDTs they issue are backed by real-world USDs. This has never been proven. A collapse in USDT would hit bitcoin (and all cryptocurrencies) hard.
My gut feeling is it will happen sometime. Any bubble - any asset rising 100 times in under 10 years - is going to attract both leverage and crooks.
Conclusion
I think the bitcoin network is stable, tested, growing and legal enough that it will still be around in ten years.
Crypto is the ultimate "risk-on" asset. Bitcoin has fallen around 50% since its highs early last year. I plan to buy some when the correction ends, or is over, using Hedgeye for market timing. Its so volatile, and the risks are so great (Tether), I don't want to hold it through a down market.
Or wait for Tether to crash/de-lever the whole crypto market so badly that no one wants to buy. Then nibble at it.
AIT released disappointing 2021 results, and the stock price dived 9%. A quick update.
Drop in Income
AIT's 2021 "Income available for distribution" was down 11%, or SGD 12.6m.
The culprit was Income tax expenses, up SGD 50m, "mainly due to higher deferred tax liabilities arising from acquisition of aVance 6 and annual revaluation; together with lower current income tax resulting from reversal of dividend distribution tax (“DDT”) provision in FY 2020." In English, 2020's income was artificially inflated by the reversal of a dividend distribution tax provision; now 2021's income is back to normal. But I don't know how much of the 50m this contributes to, and how much of the remainder is a one-off.
Other than that, their numbers look OK. 98% of rent was collected, though only 11% of the properties were populated. Rental reversions were 5.5%.
Risks
Longer term, the risks I see are:
Cyclical Property Downturn
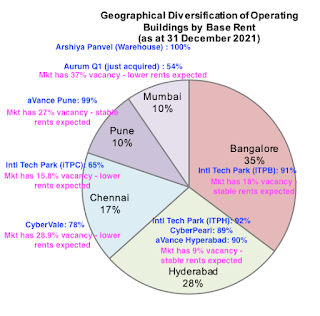
Here are their properties/areas. The blue numbers are occupancy rates. The pink text gives the vacancy rates in each property's micro-market:
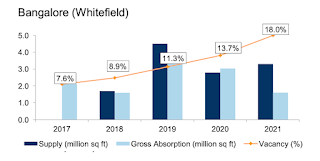
Their Chennai, Pune and Mumbai micro-markets also have high vacancy rates, from the teens to the 30's! A bit worrying.
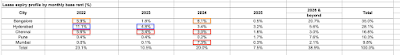
Fortunately, they don't have many lease expiries in these oversupplied areas (red, below). Most upcoming expiries are in the strong hyperabad market (blue):
They've probably planned this, so hopefully they can make it through the downturn without much DPU loss.
Work From Home
This has been in the back of my head bugging me. Technology or Business parks are just cheap offices with server and equipment rooms attached. Mostworkerswantto work from home at least a few days a week. Most IT work can be done remotely. And most Indian IT professionals are paid enough to hire help to look after the children. Even working from home one day a week will cut office space demand at the margins, leading to rental drops for the fixed office supply. We may see this over the next few years of lease renewals.
Growth
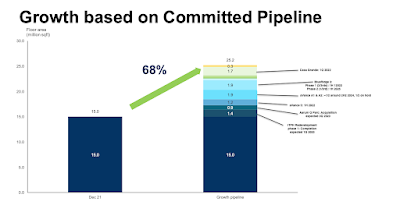
Their pipeline looks good:
Leverage and Capital Structure
Will they have to raise capital?
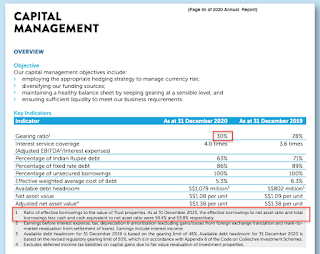
They say they only have a gearing ratio of 35%, and debt headroom of nearly SGD 1bn. I could not calculate 35%, either from their Supplementary Info or Balance Sheet. I get 40-45%. I also see different numbers in their 2020 Annual Report. So I don't know how they calculate their leverage:
Anyway, MAS' 50% leverage limit does not apply to Business Trusts, so its voluntary for AIT. Their leverage ratio can be whatever they say it is.
Everything depends on their debt headroom. In 2021, interest and dividends paid equalled CFO. But CFI outflows were more than CFO, resulting in a large debt increase.
AIT has only raised capital once after their IPO: a small SGD 150m private placement in November 2019. It was mildly pro-forma DPU accretive (p4).
Conclusion
I like AIT's long term track record of growing DPU. They have good tenants, long property tenure (or freehold), and an expansion plan in progress. I expect short term hiccups from the exchange rate and the property cycle as part of doing business.
They will probably have to raise equity soon, as interest plus dividends paid now equals CFO. Thats OK, as long as its not dilutive.
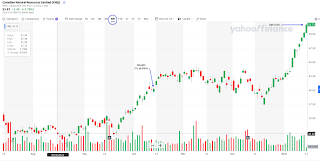
I bought a 2% position in CNQ 3 months ago, in the last month its up 20%. Its starting to look parabolic:
I like this company and want to hold it for the next few years.
But I expect a correction around 2Q, which would hit oil. CNQ is a high beta oil stock. Short term, its way, way overbought. And 2Q is only 10 weeks away, while the market is forward looking.
Sold 1/3rd of my position, @ CAD 64.44, profit 1.9K CAD or 29%. Will sell more if it goes higher and my outlook stays the same.