Wednesday, October 4, 2023

Sold VET and WHC

Exited these trading positions, because VIX is approaching 20.  The market could start cascading down as VIX approaches the 30s.

For VET:

  • OVX is in the mid 30s.
  • Oil is weakening in Hedgeye's trend signal (but still bullish).
  • VET's chart has a big high-volume-red-candle on Tues night.  Normally one red candle won't make me sell, but combine it with the other stuff.

For WHC, its a harder decision, the chart looks OK - it may keep going up:


I am probably leaving some money on the table here.  A short term trader would probably buy it today and sell a few days later.  Especially as VIX enters the 20s into a choppy market.  But I still decided to sell now since I'm free today, and may not be able to trade later.

Small profit on both trades.

Saturday, September 30, 2023

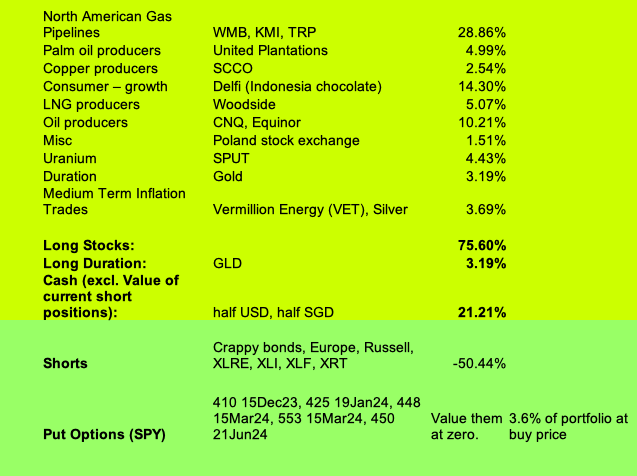
My Positions

Still think we're in a market correction heading into a recession.

Trades:

  • SPY put options are now mostly in the green, but still have a lot of upside - still holding 'em.
  • Decrease my VET holdings a bit when WTI was overbought and VIX rises into the high teens.  Energy equities can get pounded by the wider market even if energy keeps rising.  I'll keep my lower-beta, cash generating, "blue chip" stocks (Woodside, Equinor, CNQ).  WHC's price action has been strong, so I haven't trimmed it.
  • Use the last-2-day rally for the month-end-markup to add more shorts: Regional Banks (KRE), Poland (EPOL), Airlines (JETS) and Tech (XLK)
Investments:
  • Uranium's (SPUT's) price rise has increased it to 5% of my portfolio.
  • Longer term, its time to start writing a shopping list.  I think it'll be a shallow recession like 2001, not a crisis like 2008.  2024 is an election year, expect the government to drop rates and pump like crazy once the recession starts.
  • But there's no rush to buy.  I can get 4.8% on USD in Interactive brokers and 5.2% in Tbills.  "There is an alternative".

Wednesday, September 6, 2023

My Positions

For investments:

  • Increased TRP to my max of 5%.
For trades:
  • Sold off a lot of gold last week.  Expect higher inflation this month, real rates fall, gold rises.  May get a chance to buy it back cheaper.
  • Copper is not bearish anymore.  Cover my small COPX position.  Was a mistake to hold so long (often against the trend) from middle of last year.
  • Silver bullish again, bought a 0.5% position, may go to 1%.  
Update: 18/Sep/23:
  • Cut Silver, it broke down
  • Took a 1.5% position in WHC, Aussie coal.  Expect price spikes if this winter is cold.  Would go up to 3%.

Update: 27/Sep/23: In the last 2 weeks I:
  • Cut XLF.
  • Took another 1.5% position in WHC.

Update: 28/Sep/23:
  • Take profit on some VET, sell 1%.  Bring down my trading pisition adn VIX nears the 20s.

Sunday, August 27, 2023

Notes on TC Energy (TRP:TSX)

I love gas pipelines, like Buffet's toll roads.  This company owns pipeline throughout North America.  The stock has fallen due to crappy management, and is below its 2020 price.  Its got world class assets, and I don't think bad management can destroy it no matter how hard they try.  Lets take a look.

Segmental Breakdown and Pipeline Details

From their 2022 AR.  "EBIDTA" below means "2022 Comparable EBIDTA".

The business is transporting gas over a continent, so we gotta look at a map to understand it:


US Gas Pipelines (41% EBIDTA):
  • Columbia Gas (6): Transports gas from the Marcellus to markets and pipeline interconnects throughout the U.S. Northeast, Midwest and Atlantic regions.
  • ANR (7): Transports natural gas from various supply basins to markets throughout the U.S. Midwest and U.S. Gulf Coast.

Canadian Gas Pipelines (28% EBIDTA):

  • NGTL (1): gathering and processing from producers in the WSCB to the Canadian Mainline.
  • MainLine (2): Transports gas produced in East Canada to West Canada.  
  • Costal GasLink (26): Pipeline under construction to ship gas from WCSB to the west coast for LNG export.  Its construction has had bad cost overruns, but is now 91% complete.  Expects to be operational 4Q23.
Mexico Gas Pipelines (8% EBIDTA).

Liquids Pipelinse (14% EBIDTA):
  • Keystone (not shown above, see p62).  Transports crude oil from Canada to and through the US for refining, down through Oklahoma to the GOM.  Canada cannot refine most of its crude, which is exported by pipeline to the US (87% of total crude in 2020), and Keystone transports around 14% of that.  There were (costly) expansion plans (Keystone XL) approved by Trump which were cancelled by Biden.

Nature of Revenue and Pricing

Nearly 80% of their EBIDTA is regulated (p28):
  • Meaning that rates negotiated with customers have to be approved by government agencies (FERC - US, CER - Canada) to prevent price gouging. 
  • The Canadian Mainline (7% of EBIDTA) was built before US shale gas was discovered, and has since struggled to compete with cheap US gas coming from the Appalachian Basin (Marcellus).  It has no pricing power.  In this case prices drop - regulation doesn't matter.
So regulation does limit upside a bit, while not protecting downside.

I think the 2020's will be the decade of inflation.  Are TRP's revenues protected against this?

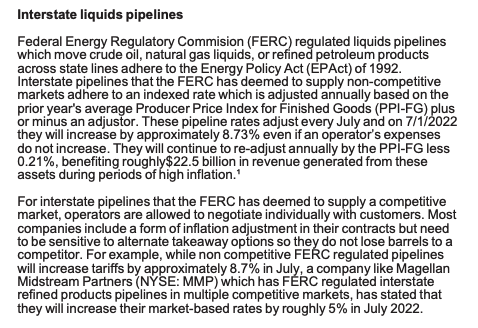
Some FERC rates are automatically-inflation adjusted.  Depending on the pipeline classification, rates are automatically adjusted every year, or inflation adjustments are written into the contract with the customer:


I could not google any information on wether the Canada Energy Regulator adjusts rates for inflation.  The company says NGTL "operates under the terms of the 2020-2024 Revenue Requirement Settlement which includes an ROE of 10.1 per cent on 40 per cent deemed common equity." (p178)  To me, this does not sound like it adjusts for inflation.

Here are some hints that it does take inflation into account:


Source: finchat.io

I could not get any details.  Not sure if they will adjust the entire tariff by the inflation rate, or only the part reflecting increasing maintenance costs (while excluding build costs from the past).  This would be a small adjustment as maintainence costs are low for gas pipelines.

So for inflation protection:
  • US pipelines adjust for inflation.  Yearly if its a "non-compeditive" pipeline.  For "compeditive" pipelines, its based on the contract, so will depend on if you have pricing power.
  • Not sure if/how Canadian pipeline tariffs adjust for inflation (?)
  • If an area has too many pipelines and not enough demand, prices will go down, regulation and inflation adjustments don't matter.

Cashflows

Dividends are lower than CFO, but CFI is very high due to capex on new projects.  CFI plus dividends has exceeded CFO in many years:


Projected capex is below.  Maintenance capex (part of CFI) is approximately ~2bn per year.  I've annotated for their later Costal GasLink blowout:


So its not until 2026 that they'll start paying down debt.

Debt

At end 2022, debt was 51bn: 41bn in loans or notes, plus 10bn in  Junior Subordinated Debt.  Thats unsustainable, at 8X 2022 CFO, or 12X 2022 FCF.  CFO should grow (probably another 3bn in the next 5 years) as the new projects come online, so that makes it a bit better.

Debt maturity (I have not broken it down into USD/CAD debt):


What is the effect of rising rates on their debt?  I went through years of annual reports - they did not make it easy - to consolidate their debt issuance.  They have:
  • 30bn fixed rate debt
  • 8bn floating rate
  • 3bn unknown
  • 10bn Junior Subordinated debt. (p195).  These are fixed rate for the first ten years,before converting to floating rate.
If all debt due by end-2027 is refinanced at 9% (The 20 year risk free Canadian rate is ~3.7%, the US one is 4.5%.  I'm using a high rate for high debt and shitty management)...then their 2022 results would have ben lower by 900m, a 20% reduction in FCF.  The same stress test for WMB and KMI give 10% and 7% reductions respectively.

The key thing for this company is no more cost blowouts till 2025, then being able to pay down debt after that.

Risks

  • Canada's carbon tax is $20/ton today, but due to increase to $170 by 2030.
  • The company has a history of operational problems: Milepost 14, Keystone pipeline leaks, Columbia gas line pressure drop. Concerned it may be a cultural issue.
  • To much debt, especially when the Junior Subordinated debt converts.
  • They may move into ESG and renewables, which have lower returns.

Valuation

At CAD 48, its trading at a 7.75% yield.  Thats paying out 75% of their 2022 FCF.

New projects coming online should increase CFO by half in 3-5 years, but they need to pay down debt.

Misc

I don't know the withholding tax rate.  Interactive Brokers usually charges me 15% for Canadian stocks, but TRP has significant operations in the US, so it may be higher.

Edit: Nov 2023: Confirmed my witholding tax is 15%

The stock plunged three weeks ago on news of the Keystone spinoff, then recovered.  It looks like capitulation, so that may be the turning point.

I have bought a 2.5% position, and would go up to 5%.  My max size for this is half that of WMB or KMI, who have less operational and financial risk.

References

Wednesday, August 9, 2023

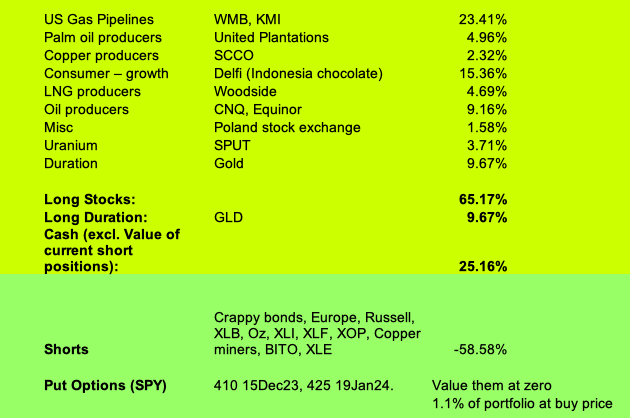
My Positions

 Haven't changed much.

  • Rising oil has pushed the portfolio value up a few percent in the past week.
  • 2 nights ago, added shorts for XLI, XLRE and XRT.  Added -7% to my short positions.  Now at max, cannot add more to these positions.
  • Also bought more SPY puts, this is the last time I buy them.
I think this is the turning point, and the market corrects in August.

I am looking to:

  • Remove my 1.5% SLV position, as silver isn't performing.


Edit: 15-aug: Sold silver at a loss, moving on.

Saturday, July 29, 2023

Bought Vermillion Energy (VET)

Hedgeye's oil price Risk Range went to bullish trend on the 17th July after being bearish for a year.

Looking for something to trade, I came across Vermillion Energy:

  • Half its 1Q22 revenue is from oil (2/3rds of that from Canada, 1/3rd from Europe), and half from gas (70% of this half is priced in AECO (Canada), 30% from Europe.  in Q2, we expect 40% from Europe).
  • Leverage on the high side, they are concentrating on reducing it.  Mostly fixed rate.  Negligible dividend.  Some buybacks.
  • 2P reserves of 14 years, not great.  Read somewhere there are some questions about how they depreciate their reserves.  No breakdown by oil and gas.
  • Its a high beta stock: it dropped 60% from the peak last July's peak to the trough.  Could be due to Canada's oil and gas pricing varying more than WTI (due to lack of transportation from Canada) and the wild variations in European gas pricing.
  • 1Q22 Annualised EPS is $8, trading at CAD 18, thats less than 3X a year's earnings.  Not a lot has to go right.
  • European Windfall taxes end in Dec 2023....if they are not renewed.  Pro forma, removal of the windfall tax would have added another 5% to their 1Q22 earnings.
Its a trade - not a Buffet-like stock to pass to your grandkids.  Hopefully the trend lasts a few months or quarters.  I'll sell it when Hedgeye's oil trend changes.  Would not hold a stock this volatile thru a downturn.

Bought a 1% position last night @ USD 13.25, after the stock dipped for 4 days.  I would go up to 3%.  The problem is it rarely dips enough to take a big position.


My positions haven't changed much:
  • The portfolio is quite oily, and has started to go up with oil.
  • Removed some shorts that changed to bullish trend.
  • Added some long term index puts.
  • Have VET and Silver in an "Inflation Trades" basket.  2% total.


Update 6th Aug 2023:
  • Increased VET position to 2.5%.  It wont go down enough to buy a big position.
  • Silver position increased to 1.5%.
  • SPX looking bearish, may buy more puts (June 24) if we get a bounce next week.  If things work out this could be my last chance to buy.

Update: 8th Aug 2023 morning: Increased VET to 3% last night.  Last night's rebound was weak.  SPX is no longer oversold, AAPL has broken down and VIX has broken out.  Look to press shorts, probably tonight.

Saturday, July 1, 2023

My Positions

 Small changes:

  • Increased 1% in SPUT
  • Increase my shorts in XLI
  • Started a small short in XLE
  • Bought more SPY puts on Friday, expiring January.
I think this bear market rally ends in the second half of this year.