Friday, July 5, 2013

Notes on GoodPack

Since I last looked at it, the profile of this company has changed a little.

Note their financial year ends June.

Cashflows

Having being leasing IBC's for the past few years, they have been able to generate free cashflows (yellow below):
But from this year onwards, Capex will rise as they go back to buying IBCs. As of 3Q 2013 (May), they have already spent 102m on PPE.  Both OCBC and DBS-Vickers predicted higher capex for 2013 and 2014.
:

Balance sheet

As of May 2013, total debt was USD 266m, offset by 176m of cash.  Although net debt is about the same as a few years ago, its now only 2X earnings.

Most of their debt is long term fixed rate (~ 4.7+ percent); Medium Term Notes:
  • Probably 25m short term bank loans
  • 100m MTN due July 2013.
  • 120m MTN due in 2016/17.
  • 30m MTN due 2023
  • 50m MTN due 2023 (issued end-Apr: not part of the 266m debt above)
Looks Like they will be taking on more debt in future.  Their medium term note program has increased from 300m to 600m, to be issued whenever they want.

Operating lease commitments as of Jun 2012 were 14m (vs 177m revenue, 47m profit, and 6m finance costs).  Few of these last longer than a year, but I think that they have to renew them, else risk their IBC suppliers becoming compeditors.


Cyclical

Would they be affected by a downturn/recession?  Probably.

From CIMB:  In 2008 and 2009: "there was a temporary dip in Goodpack’s earnings when its major clients (tyre producers) failed to fulfil their contractual obligations of moving promised rubber volumes. The sharp dip in tyre demand had caught many tyre producers by surprise with manufacturers like Michelin, Goodyear and Bridgestone suffering huge losses. With excess inventories of raw materials (rubber), Goodpack’s clients were unable to move their obligated rubber volumes. As an act of goodwill, Goodpack allowed its major clients to renege on their contracts temporarily, which hurt its bottom line. Goodpack was able to mitigate the pain by increasing its market share in the synthetic rubber transportation segment."   They do not see this occurring again.

On the positive side,  DBS Vickers predicted a bounce in tire demand (replacements) in Mar 2013, which they are still waiting for. Also due to 2 new Synthetic Rubber factories being built on Jurong Island, starting production in 2014.

Valuations

At 1.57 (SGD), trailing PE is 14.4.   Assuming 3c (SGD) earnings in 4th Quarter, forward PE is 13.  Not cheap, but not bad in an expensive market.

During the entire 2011, the stock dropped 40+% on fears of a slowdown, to a trough of 7.7 forward PE.  In 2009, the trough was a (trailing) PE of 7.2.

My guess is that from here, there's equal upside and downside: depending on if there is a slowdown/recession, or if the DBS's projected recovery occurs.

Support at around 1.30 (projected FY 2013 PE of 10.7), would probably buy there.

Sunday, June 30, 2013

Still Waiting....

After a 9 month rally: finally a pullback! Due to the Fed's comments on 'tapering'.  And something about China.

My gut feeling is that this will probably be a 10-20% correction.  Don't think we reached the euphoria seen at the end of a bull market.  Maybe we get a *real* bear 1 or 2 years later.

We are also in the twelfth year of a secular bear market, which usually last 12-18 years.  I must consider the possibility, however wrong it feels, that the secular bear is over, and its 1982 again.

And there is the possibility that the market 'corrects sideways' for a long period, without giving me a big crash.

I am changing my investment strategy a little to account for the unknowns.  Using the S&P 500 as a yardstick, but in steps all the way down:
  a) Wait for a 15% decline (for now: S&P 1434), if it occurs, move up to 20% invested.  15% declines happen once every few years.
  b) If a further 15% decline occurs, move up to 60 % invested.  These 30% declines are rare.
  c) If a further 10% decline, go to 100%.

Nothing magical about these numbers, just a way to get *slowly* get into the market.  After a 3 year bull market, be very slow and careful.  I'll still probably be mostly in cash for the next few years.


What to buy?  Looking at the US and European stocks (multinationals), everything is expensive - PEs in the high teens (and these are not trough earnings).  The Singapore market is similarly expensive, but there are a *few* decent companies trading in the low teens.

Wait to see if the correction continues.  The S&P is retesting its trend line and moving averages.

Saturday, April 13, 2013

The Car Industry

I like Volkswagen's branding, due to their ownership of multiple brands at different price points.


Unlike Mercedes or BMW, for instance, who risk diluting their brand as the move downmarket to sell cheaper and smaller cars.  Or Toyota, who created an upmarket car, but can't quite break into the luxury market...because its still a Toyota.  Always a bad idea to have your branding based on a single name.

Volkswagen have increased their European market share from 18% in 2005 to 24% in 2012, due to aggressive financing (e.g.: zero percent loans) and scale.

I took a look at their numbers.  It did not take long.  Although revenues and profits have increased nicely:


Free cashflow generation has been low.  Over the last ten years, the 73b profits generated has turned into just 9bn free cash flow:

The culprit is the finance/leasing part of the company.  Despite high capex - higher than depreciation - the Automobile production generated free cashflow every year.  But increased financing of new customers  drains most of the cash generated.

So the long term, increasing car sales consumes most of the cash generated.  As well as the normal drain on working-capital (increasing inventories/receivables), for cars, it also involves financing your customers to buy their vehicles, and building expensive factories.


An optimist could say that 37bn was spent over the past 10 years building the business:  it has quadrupled their revenue, and increased they profits 5 to 10 times.  But companies in other industries can do this and generate free cash flow while doing so (e.g.: Richemont, Coca Cola).

Volkswagen probably will not need to raise money from the stock market soon.   And they are probably better than their European competitors.  But they are the best of a bad lot. 

Toyota has a similar pattern.  Over the same 10 years, 8 trillion yen of profits (net income) turned into 280bn free cashflow consumed:

Again the problem is with the finance segment, though Toyota spent more of this on building up its fleet-for-lease, rather than on financing for buyers.

BMW is even worse, generating free cashflow in 2 of the past 10 years:


Daimler (Mercedes) over the past 8 years:


These are the best companies with the strongest brands in the industry.  The car industry looks like a lousy place to invest.

Monday, March 25, 2013

iWatch vs Swatch

Apple's rumored iWatch would not be a watch, but a complement to an iPhone.  Probably some snap around bracelet, with a wireless connection to it.  With, for example: automatic passcode unlocking, NFC for automatic payments, help finding your lost phone, etc.


Samsung has also confirmed they are also working on a watch.

The Swatch CEO has come out to say that he does not think its a big deal.

Yes, luxury mechanical watches and an electronic iPhone-complement device are different products, addressing different markets.  One is an intricate, delicate piece of machinery - the only piece of jewelery men can wear.  The other would be a convenience.

For investors in Swatch and Richemont, if the iWatch does take off like the iPhone did 6 years ago, the key question is: Can you wear both the iWatch and your mechanical timepiece at the same time?  I don't think so.  At best, its redundant.  At worst, you look like a pretentious dick.  Dress watches - for special occasions - may not be affected, but any watch that you wear to the office would be no longer required.

These products may never even see the light of day - large companies have dozens of R&D projects at any time, many of which will die.  It seems a bit extreme to run from a rumor.  However, given Apple's track record, its very difficult to predict how the new products they define will shape our world, when the only thing you know is the old products.  And a reminder of all the companies that Apple has destroyed.

Is the age of mechanical watches coming to an end?


Monday, January 21, 2013

Secular Bear Markets - don't wait for another big crash

I'm now waiting for a recession or bear market.   As an amateur doing this part time, the safest way is just to wait for a crisis, which seems to happen at least every ten years.   I dream the market drops 40%, like in 08, and I get to buy stocks on the cheap.  I'll probably be waiting a few years more. 

From "The Great Super Cycle" by David Skarica:
  • Since 1900, four secular bears lasting 15-20 years
  • Secular bull starts when valuations are compressed: In 1949, S&P's PE ratio was 9.1, In 1982 it was 6.6.
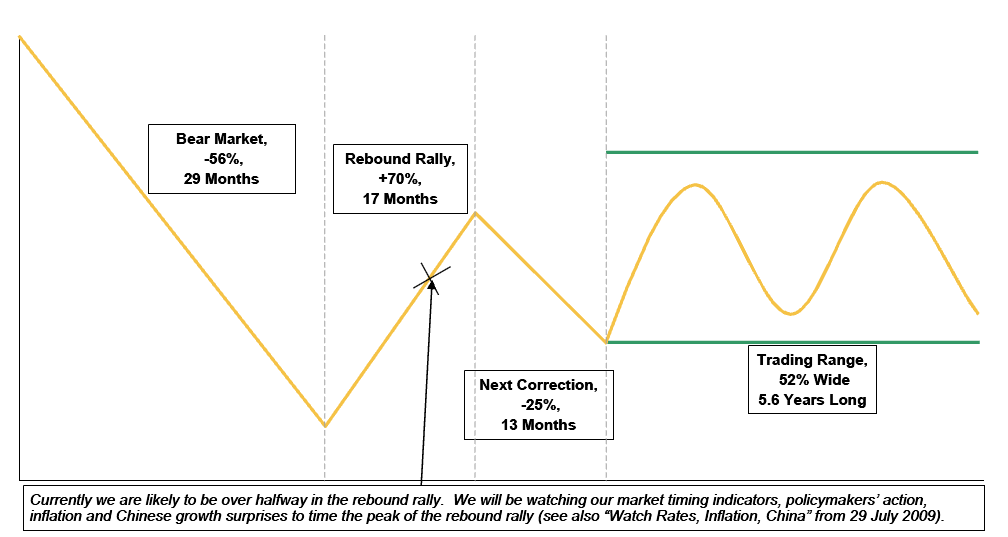
  • Majority of decline occurs in first half of secular market.  (We have probably passed this phase now).  In the first half of the secular bear market, you see the busts.  After the bust, then after the rallies, a long trading range followed.  In the second half of all these secular bear markets, volatility dried up. In the case of the 40s and late seventies, there was not one bear market greater than 35%.
          The last 4 bear markets show this behavior.

          Chart that averages out past secular bear markets
  • The long trading range is greeted with high inflation. (Inflation adjusted charts).
  • Therefore, if history follows suit, we will not see a crash in the current decade.  Rather, what will happen is that the market will trade sideways, with inflation picking up.
  • Secular markets do not end with a crash.  They end when the market has not done anything for a period of years and investors are no longer interested.  They end with a whimper, not a bang.
  • Average of 6 rallies in a secular bear market.  The current one has seen 3.
  • If the market peaks in 2010 or 2011 and sees another bear market, it will probably be minor in nature in nominal terms.  The 1909-11 bear market was 27.4%, the 1938-39 one was 26.2%, in the 1976-78 bear the market dropped 19.4% on the S&P and 26.4 % on the DJIA.   
Will this be similar to the 73/74 cyclical bull market? After a 6 year rally, the S&P only dropped 26% in the 81-82 recession.  But it was worse in real terms: There was an oil shock then and US inflation from 1978 to 1981 was over 10%.  I don't see any sign such high inflation can happen now.

If history repeats itself, I should NOT expect a repeat of 2008 bear market.  Expect a flattish market with smaller dips.  I should start buying on a smaller (25-30%) decline.  At that point, be prepared to go all in as it may take off from there.

Monday, December 3, 2012

Prada

3rd largest luxury handbag brand/company in the world.  For fashion and leather, the Prada brand had 2011 sales of 2b Euros, compared to:
  • LV's sales of 8.7b (includes all LVMH's fashion and leather brands - Fendi, DKNY, Loewe, Celine and others - majority of sales are probably from Vuitton).
  • Gucci's 3.1b (part of PPR).

What do they do?

In 1H12, 62% of their (company wide) sales were leather goods (excluding footwear), so we'll concentrate on that.  In Asia, I would say that all the 'fashion' stuff is really just there to decorate handbag shops.

Prada bags are roughly the same price as LV, in the middle of HSBC's luxury pyramid:


I believe Prada is targeted at women over 30.  Their sister brand, Miu-miu, has bags around 30% cheaper, aimed at younger people.

Prada also owns Church and Car Shoe - they are insignificant so ignored here.

Prada is more fast-moving than LV: they are more design or fashion driven.  As a they were initially a clothing brand, they have collections and fashion shows every year.  As much as 70 percent of its products are renewed every year.  They also hold 'flash sales' of limited edition items available one-time only, and constantly add new collections (e.g.: Valentines day).  Although their signature look is "black leather with a small gold logo", they have a larger variety of bags with different shapes/colors, compared to LV or Gucci:


Although LV's bags have changed (e.g.: neverfull), their colors and logos are the same as from ten years ago.  Even their new designs (e.g.: Athena hobo) are 'logo driven'.  Every bag I see  in an LV shop had an instantly recognizable logo.  Good, because the bags are 'timeless' and instantly recognizable.  Bad, because they are becoming boring and ubiquitous.

Other than that, Prada's business model is similar to Vuitton:
  •  Opening new retail outlets:

          They intend to add 100 outlets in 2012, 60 in 2012 and 60 in 2014.

          From DBS (Mar 12), they still have less than half LV's outlet numbers.

           Still have low penetration in China and the US:


  • Reducing sales through franchise stores (down to 25 stores in July 2012):

  • Reducing mark down policy: DBS Mar 12: "Since 4Q09, Prada has cut down price reduction rate for certain products from 50% to 30% and some from 20% to 10%".
Interesting that Prada spends a lot less on marketing and advertising than LVMH (5% vs 11.5% of sales in 2011).

Made in China?

Unlike Vuitton, which manufactures its products in-house in Factories in Europe and California , Prada manufactures all over the world.  From the DBS report: "It outsources c.80% of its product manufacturing processes to  c.480 external manufacturers (semi-finished and finished products) while keeping the balance 20% of processes in-house, hence ensuring at least one important phase of the production process is performed internally. Prada has a total of 11 in-house factories (10 in Italy,  1 in England)."

About 20% of Prada's collection (including some bags) are made in China.   "Sooner or later, it will happen to everyone because [Chinese manufacturing] is so good," Prada designer Miuccia Prada said in an interview.  "What do you care where I make my shoes?" says Prada Group NV Chief Executive Patrizio Bertelli. Where local laws permit, Mr. Bertelli says he'd prefer to insert a "Made by Prada" tag in his products.

I think that Prada is doing this because, as they are more design and fashion orientated, they need faster and responsive manufacturing capabilities.  Unlike LV.  I don't know if this will become an issue: Coach and Burberry manufacture in China, but their bags range from several hundred to SGD 1.5K - almost half the price of a Prada or LV.  I believe that, for an Italian luxury brand, people do not expect their bags to be made in China.  And in Prada's price range, people do want to have to search for the hidden label to see where something is made.

Maybe people will accept it, maybe not.  This is possibly a serious threat to the image...the authenticity of the brand.

Management

Company is led by Micciu Prada (63) who handles fashion, and her husband Patrizio Bertelli (66) who handles business.  This article suggests that their children (early 20s) may not be part of the business.

This article mentions a high turnover of execs due to Bertelli's style.

An old 2001 article: Bertelli, some Prada people say, wants to go mass-market by buying brands such as Italian tennis-shoe company Superga and sticking the Prada name on everything from fragrances to jewelry. " 'We don't see ourselves as a luxury company in strict terms,' says Bertelli, who points out that people who buy Rolex watches also buy Swatches. "  Fashion or Luxury?

Could not find Prada's conference call transcripts.

The company is under family control: almost 80% of Prada SPA shares are held by PRADA Holding BV, leaving a ~20% free float.

Profit breakdown

Their largest costs are COGS, which as a proportion of sales has been dropping steadily over the years.; Probably due to the increasing proportion of retail sales:

This has givem both top and bottom line growth for the past few years.

Their expansion over the years comes at a risk of increasing operating leverage (e.g.: fixed costs from store rentals). Their operating costs are given in 2 breakdowns (footnote 35).  The main one is personnel, followed by Admin: Its not really possible to guess which are fixed costs and which are variable:


The largest costs in in the 2 different breakdowns are 'Selling' expenses and 'Staff' costs.  Fixed or variable?  I do not know if Prada sales associates earn a commission or not.  Some brands pay commission (6% given here), some don't (Vuitton).  COGS is probably variable, since most of their production is outsourced.

Liabilities

From the 1H12 results, balance sheet looks clean. Debt has steadily been shrinking since listing in 2010.  Retirement liabilities of 42m are insignificant compared to the 289m half-year's profit.

Only possible issue is the high operating lease commitments: 254m due within 1 year.  And 771m due in the next four years.  A significant fixed cost.

There one contingent liability: The Shareholders’ agreement signed between PRADA spa and Al Tayer Insignia llc for the development of a Prada and Miu Miu network in the Middle East provides that the parties may exercise an option whereby PRADA will buy back up to 20% of PRADA Middle East fzco shares.

Cashflows

CashFlows from operations has been higher than earnings every year since listing.  The difference is mostly depreciation and amortization:

Working capital is usually negative (but very small compared to the depreciation and amortization).  WC was only positive in 2009, as inventories and receivables were drawn down, probably due to recession:

CFI has been less than CFO, generating free cashflows every year:


Conclusion

Seems to be a cash cow, and growing.  In that respect, its like Richemont: a cash cow with high operating leverage, but little or no debt.

The risks are:
  1. Its a single brand only, maybe two....Prada and Miu-Miu bags are kind-of similar. More than LV or Gucci, Prada relies on constant updates to get people to buy.
  2. The "Made in China" issue.  Long term, it may threaten the desirability of the brand.  Fashion vs luxury?
  3. Has not been listed for long enough to see how demand is affected during recession.
See how they sales and profits are affected during a recession first.  If I do buy, I must remind myself to buy less, due to 1. and 2.

Tuesday, November 13, 2012

Quick notes on Swatch

1) Omega is trying to move upmarket, having:
       - increased prices dramatically (~30 to 50%) in the past few years, with
       - more marketing: Olympics and James Bond, and
       - pulling stock from third party stores while relying on their own boutiques.  Who no longer give the expected 20% off MSRP.

If successful, they will end up like Rolex: widely known to the general public as an expensive watch to buy when you've 'made it'.  Instead of 'the watch for when you cannot afford Rolex'.  I think it will take 5-10 years for the general public's perceptions to change, but Swatch (being family controlled) should be disciplined enough to pull it off.

Those buyers priced out can always buy a cheaper brand instead: its common here to see am Omega boutique next to a Longines or Tissot one.  I love Swatch's long term branding strategy, market segmentation...and their profit/cashflow numbers.  Just wish they would give more transparent: giving breakdowns between their high end and low end segments, make conference calls available, and give a better breakdown in their P&L statement.


2) In late March, HSBC downgraded Richemont to neutral on fears that high-end watch demand may be starting to see a downturn (poorer sales and rising inventory at Hengdeli), partially due to a decline in 'gift giving' due to China's leadership transition.  They were more optomistic on Swatch due to its lower end brands.  HSBC turned out to be a a bit early, but still take note of this to see how accurate their reading of the (Chine) watch market was.

I still like Richemont, and would buy on any serious downturn.